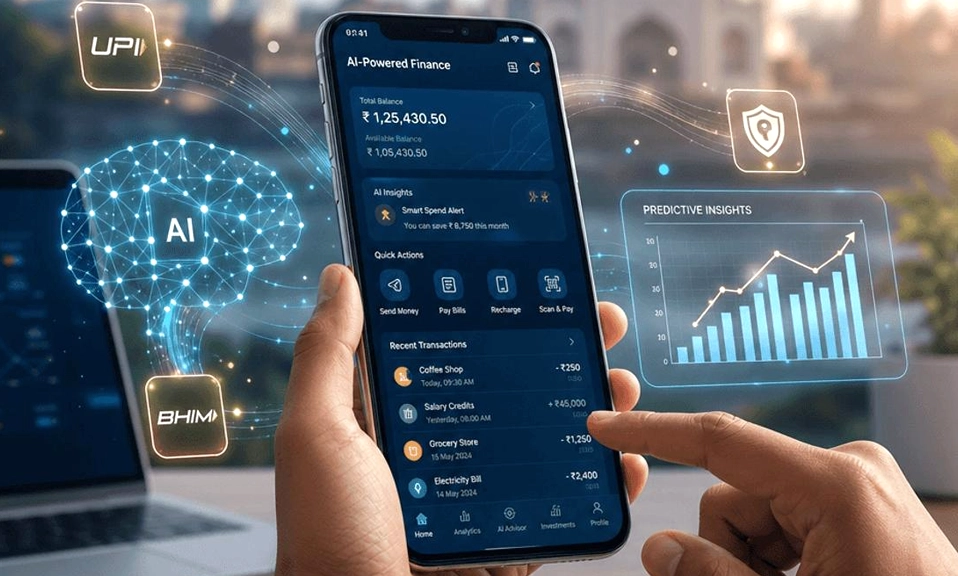
Artificial intelligence has moved from the realm of science fiction into the mundane—and nowhere is that more apparent than in personal finance. In 2026, AI is not just helping you find a restaurant or draft an email; it is categorizing your spending, negotiating your bills, optimizing your investments, and even flagging fraud before you notice it. The promise is not that AI will make you rich overnight. It is that it can handle the repetitive, time-consuming, and error-prone parts of money management, freeing you to focus on the decisions that actually require a human brain.
But automation is not a substitute for understanding. The same tools that can simplify your financial life can also lull you into complacency or expose you to privacy risks. The key is to know what to automate, what to keep manual, and how to use AI as an assistant rather than an oracle.
Here are seven financial tasks you can automate with AI today—and what to watch out for with each one.
1. Budgeting and Expense Tracking
The task: Categorizing every transaction, tracking spending against a budget, and identifying where your money is actually going.
How AI does it: Modern budgeting apps use machine learning to automatically categorize transactions—separating groceries from dining out, transport from subscriptions—and to detect patterns you might miss. Some go further, analyzing your spending behavior to predict future cash flow, flag unusual expenses, and suggest adjustments in real time. Apps like Cleo, Copilot Money, and YNAB (which has integrated AI features) can generate personalized insights, such as “you spend 30% more on weekends” or “your subscription costs have increased by $45 this year.”
What to watch for: AI categorization is not perfect. A transaction at a combination grocery store and café might be misclassified. Review the categories periodically and correct errors—the AI learns from your corrections. Also, be aware that some budgeting apps require full access to your bank accounts; choose providers with strong security and transparent data policies.
2. Bill Negotiation and Subscription Management
The task: Monitoring recurring bills, identifying price increases, negotiating lower rates, and cancelling unused subscriptions.
How AI does it: Services like Rocket Money (formerly Truebill) and Trim use AI to scan your bank statements for recurring charges, flag price hikes, and even negotiate on your behalf with internet, phone, and insurance providers. The AI can identify subscriptions you haven’t used in months and prompt you to cancel. Some credit card issuers now offer AI-powered subscription tracking that alerts you when a free trial is about to convert to a paid plan.
What to watch for: Negotiation services typically take a commission (often 30–40% of the first year’s savings). Read the terms carefully. Also, some services require you to share your banking credentials; use a provider that uses read-only access and strong encryption. And remember: AI can cancel a subscription, but it cannot know whether you actually intended to keep it.
3. Automated Savings and Micro-Investing
The task: Setting aside money consistently, investing spare change, and rebalancing your portfolio.
How AI does it: Robo-advisors like Betterment, Wealthfront, and Schwab Intelligent Portfolios use AI to build and manage diversified portfolios based on your risk tolerance and goals. They automate contributions, reinvest dividends, and rebalance your holdings when they drift from your target allocation. Micro-investing apps like Acorns round up purchases to the nearest dollar and invest the difference. AI can also analyze your cash flow and automatically transfer a portion of your paycheck to savings or investments on a schedule you set.
What to watch for: Robo-advisors charge fees (typically 0.25–0.50% of assets annually), and their algorithms are not immune to market downturns. They are designed for long-term, passive investing—not for market timing. Also, automated savings can lead to “set it and forget it” complacency; review your contributions annually to ensure they still align with your goals.
4. Tax Preparation and Optimization
The task: Gathering receipts, identifying deductions, and filing tax returns accurately and on time.
How AI does it: Tax software like TurboTax, H&R Block, and TaxAct now uses AI to scan uploaded documents, automatically populate forms, and flag potential deductions or credits you might have missed. Some platforms offer AI-powered chatbots that answer tax questions in plain language. For freelancers and small business owners, AI tools can categorize expenses, track mileage, and generate quarterly estimates.
What to watch for: AI tax tools are only as good as the data you feed them. They can miss complex situations (multi-state filings, foreign income, cryptocurrency transactions) and may not catch every deduction. For anything beyond a straightforward return, consider consulting a human tax professional. And always review the final return before submitting—AI can make mistakes, and you are ultimately responsible for what you file.
5. Debt Management and Repayment Planning
The task: Tracking multiple debts, choosing a repayment strategy (avalanche vs. snowball), and making payments on time.
How AI does it: Apps like Tally and Debt Payoff Planner use AI to analyze your debts, calculate interest costs, and recommend a repayment strategy based on your preferences and cash flow. They can automate payments, send reminders, and simulate different scenarios (“what if I pay an extra $100 per month?”). Some AI-powered financial assistants can also negotiate with creditors or recommend balance transfer options.
What to watch for: Debt management is a sensitive area. AI can suggest a strategy, but it cannot make the trade-offs for you—for example, whether to prioritize the highest-interest debt or the smallest balance for psychological wins. Be wary of any service that charges upfront fees for debt negotiation or promises to “erase” debt; these are red flags for scams. Always prioritize paying off high-interest debt (like credit cards) before lower-interest debt.
6. Fraud Detection and Real-Time Alerts
The task: Monitoring accounts for suspicious activity and alerting you before unauthorized charges become a major problem.
How AI does it: Banks and credit card issuers have used AI for fraud detection for years, but the technology is now reaching consumers directly. Apps like Truecaller and Hiya use AI to identify spam calls and potential scams. Credit monitoring services like Credit Karma and IdentityForce use AI to detect unusual activity across your credit file and alert you to potential identity theft. Some AI-powered banking apps now offer real-time transaction alerts and the ability to freeze your card instantly from your phone.
What to watch for: AI fraud detection is not infallible—it can generate false positives (flagging a legitimate purchase) or miss sophisticated fraud. Do not rely solely on alerts; review your statements regularly and enable two-factor authentication on all financial accounts. Also, be cautious about sharing your financial data with third-party apps; use only reputable providers with strong security track records.
7. Personalized Financial Coaching and Goal Tracking
The task: Setting financial goals, tracking progress, and receiving personalized advice on spending, saving, and investing.
How AI does it: AI-powered financial assistants like Cleo, Charlie, and Plum use conversational interfaces to help you set goals, track progress, and make recommendations. They can analyze your spending patterns and suggest small changes—for example, “you could save $120 this month by cutting back on takeout”—and celebrate your wins. Some robo-advisors now offer AI-driven “what if” scenarios, showing you the long-term impact of different savings rates or investment allocations.
What to watch for: AI financial coaching is not a substitute for professional advice, especially for complex situations like retirement planning, estate planning, or tax optimization. The AI may also be biased by the data it was trained on or the products its parent company sells. Use these tools as a starting point for reflection, not as a final authority. And be mindful of privacy: conversational AI assistants often require access to your transaction data, so read the privacy policy carefully.
AI is changing how people
manage money by automating the routine, the repetitive, and the easily overlooked. It can categorize your spending, negotiate your bills, invest your spare change, and alert you to fraud—all while you focus on the bigger decisions that actually require your judgment.
But automation is not a replacement for financial literacy. The most effective approach is a hybrid one: let AI handle the grunt work, but stay engaged with your money. Review your automated systems periodically, question the recommendations they make, and ensure your data is secure. AI is a powerful assistant, but you are still the one in charge.
Start with one task from this list—perhaps automating your savings or setting up fraud alerts—and see how it fits into your routine. The goal is not to hand over control. It is to free up your time and attention for the decisions that matter most.