Picture this.
You land in a new country. You tap your card for coffee. No fee. You split dinner with a friend in another currency. Instant. You check your balance. It is already updated. You freeze your card from your phone because you think you lost it, then unfreeze it 30 seconds later when you find it in your jacket.
That is the Revolut promise. And for millions of people, it actually works like that.
But is Revolut a real bank? Is your money safe? And should you trust it with your salary, or just use it as a travel card?
I dug into the 2026 pricing, the new banking license, and the complaints people still have. Here is the honest answer.
The Quick Verdict
Yes, Revolut is a good digital banking app in 2026, and for travelers, freelancers, and anyone who deals with multiple currencies, it is still the best one.
For your main everyday bank in the UK and Europe, it is now finally a real bank too. For the US, it is still not a fully licensed bank yet.
The catch: Do not put all your eggs in one app. Revolut is brilliant as your main spending app, but you should keep a backup bank for rent and salary. I will explain why.
What Is Revolut, Really?
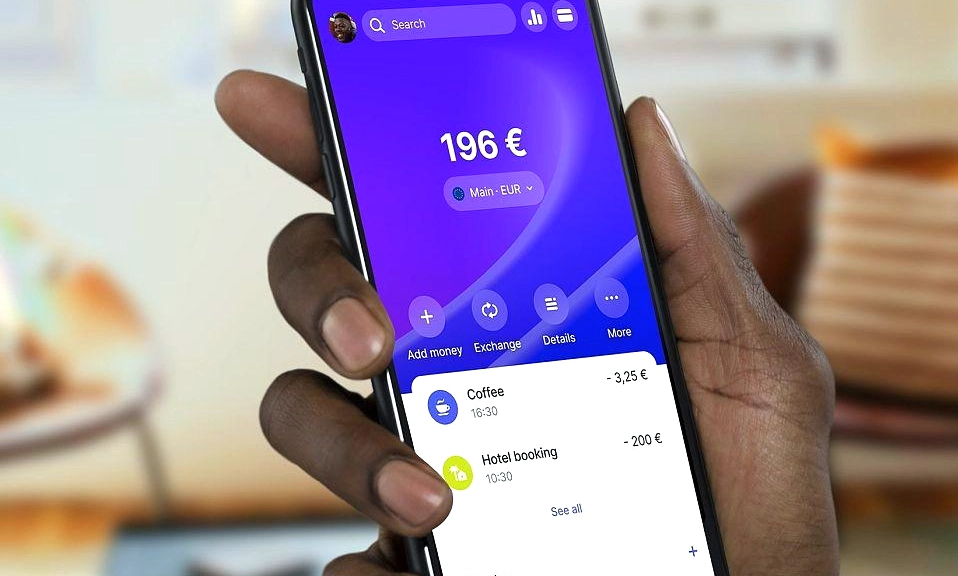
Revolut is not just an investment app: it is a bank, a savings account, a travel card, a kids account and a place to buy stocks, ETFs and crypto, all in one design-led app with about 68 million customers.
That is the best way to think about it. It is not a bank with an app. It is an app that became a bank.
What sets Revolut apart today is the breadth of features bundled into one app. Multi-currency holding and spending, international transfers, a Mastercard or Visa debit card, virtual and disposable cards, savings vaults, sub-accounts for budgeting, crypto and stock trading, travel insurance on paid tiers, airport lounge access, eSIM data plans, hotel and experience booking, joint accounts, kids accounts, and a loyalty points scheme that converts directly to airline miles.
No traditional bank does all of that. Most do not even try.
The Numbers: Is Revolut Actually Big and Profitable?
Yes, and this matters for safety.
In its FY2025 results published March 24, 2026, Revolut reported $6.0 billion in revenue, up 46%, and 68.3 million retail customers at year-end.
It also reported $2.3 billion in pre-tax profit for 2025, extending its profitability streak to five consecutive years. And by May 2026, Revolut itself said it had grown to over 75 million customers.
This is not a tiny startup burning cash anymore. It is one of the biggest banks in Europe by customers, and it is making real money.
Is Your Money Safe? The Big 2026 Change
This is the question everyone asks, and in 2026 the answer finally changed.
As of March 2026, Revolut Bank UK Ltd is fully licensed in the UK, authorised and regulated by both the Prudential Regulation Authority and the Financial Conduct Authority, the same regulatory framework as every other bank in the country.
For Revolut bank accounts in the UK, eligible deposits are protected by the Financial Services Compensation Scheme up to £120,000 per person.
In Europe, Revolut Bank UAB is authorised by the European Central Bank and the Bank of Lithuania, and deposits are covered under EU state deposit insurance.
In the US, it is different. Revolut filed for its own US banking license in March 2026, but it is not approved yet. In the US, Revolut still works through partner banks, so your money is held differently. It is still safeguarded, but it is not Revolut as a US bank yet.
Bottom line: In the UK and EU, Revolut is now a real, licensed bank. In the US, treat it like a very good fintech app, not your main bank yet.
Plans and Pricing in 2026
Plans run from free (Standard) to €55 a month (Ultra), with prices checked in October 2026.
In the UK, personal plans are free to £60 a month. Standard free, Plus £3.99, Premium £8.99, Metal £16.99, Ultra £60 as at November 2026.
In the US, it is simpler. Standard is free and exchanges up to $1,000 a month within fair usage, Premium at $9.99 raises that to $10,000 and removes the 1% out-of-hours fee, Metal at $16.99 makes it unlimited and adds travel perks.
Here is what you actually get:
Standard – Free
This is more capable than it sounds. You get a full IBAN, the Revolut card, currency exchange at interbank rates up to fair usage limits, and €200 a month in fee-free ATM withdrawals. For most travelers, this is enough.
Plus – Around £3.99 / €3.99
A small upgrade. A bit more exchange allowance, some purchase protection, a personalized card.
Premium – Around £8.99 / €9.99
This is the sweet spot for travelers. Unlimited exchange on weekdays, €400 of free ATM cash, travel insurance, delayed baggage cover, and 1 GB of eSIM data.
Metal – Around £16.99 / €15.99
A metal card, higher limits, better savings rates, lounge access, and no weekend FX fee. Good if you travel a lot or want the premium feel.
Ultra – Around £60 / €55-65
LoungeKey, huge travel insurance, higher savings rate, and concierge-style perks. Honestly, unless you travel every week, this is overkill. It only pays off for heavy travelers.
My take: Start on Standard. It is free. Upgrade to Premium only if you travel more than 3 times a year or you hit the exchange limit.
Why Revolut Is Brilliant For Travel
This is where Revolut still destroys every traditional bank.
Revolut is one of the best travel cards for spending abroad because even the free Standard plan pays in 150+ currencies at the interbank rate, with no foreign transaction fee on up to €1,000 a month and €200 or 5 fee-free ATM withdrawals.
You can hold and exchange 39 currencies in the app and spend in 150+.
That means you land in Tokyo, you pay in yen. You land in Paris, you pay in euros. No 3% foreign fee. No “we will convert for you at a terrible rate” scam at the ATM. You see the real rate in the app before you pay.
Plus, the security features are perfect for travel. Disposable virtual cards for sketchy websites, freeze and unfreeze on tap, location-based security, instant notifications the second you spend. If someone clones your card, you know in 2 seconds.
If you travel even twice a year, Revolut Free will save you more money than any other app.
The Features That Make It Addictive
Revolut is not just a card. It is a whole money system.
Vaults: Round up your spare change into savings. Set a goal for a trip, a new phone, an emergency fund. It is budgeting without spreadsheets.
Analytics: It tells you exactly where your money went this month. Coffee, food delivery, subscriptions. It is a little painful, but you need to see it.
Split Bills and Group Vaults: Split dinner in 3 seconds. No more “I will pay you back later.”
Stocks and Crypto: You can buy stocks, ETFs, and crypto in the same app. It is not the cheapest for serious investing, but for a beginner who wants to buy $20 of Apple or Bitcoin, it is incredibly easy.
RevPoints: Every spend earns points you can turn into airline miles or discounts. It is Revolut’s answer to credit card rewards.
eSIM: On paid plans, you get data abroad built into the app. Land, turn on your eSIM, you are online. No airport SIM card hunt.
No traditional bank app feels this modern. Most feel like they were designed in 2012.
What Revolut Still Gets Wrong
A real review has to be honest. Revolut is not perfect.
1. Weekend Fees
Weekend exchanges carry a 1% surcharge on the Standard plan, waived on Metal. This is because forex markets are closed on weekends, so Revolut adds a markup.
It is annoying. If you exchange on Saturday, you pay 1% more. The trick: Exchange on Friday, or upgrade to Premium or Metal to remove it.
2. Customer Support and Account Freezes
This is the biggest complaint, and it has not fully gone away.
Customer support relies heavily on AI chat, which frustrates users with complex issues. Account freezes remain a common complaint.
Sometimes Revolut freezes an account for a compliance check. Legally, they have to. But users say they get little explanation and slow appeals. The dominant complaint is support: accounts frozen, blocked or closed with little explanation, slow appeals and chat bots.
That is why many reviews say the same thing: Keep a second account for rent and salary. Use Revolut for spending, travel, and daily money. Do not make it the only place your money lives if a freeze would leave you stranded.
It has improved in 2026, especially now it is a licensed bank, but it is still Revolut’s weakest point.
3. It Can Feel Overwhelming
Open the Revolut app and you get: Banking, Exchange, Stocks, Crypto, Travel, eSIM, Insurance, Shopping, Donations, Kids, Business. It is a lot.
If you just want a simple bank account, a traditional bank app is calmer. Revolut is for people who like having everything in one place.
Revolut vs Wise vs Traditional Banks
Revolut vs Wise: Wise is better for pure international transfers, especially large amounts, and has simpler, more transparent fees. Revolut is better for daily spending, travel, and having everything in one app. For a weekend trip, Revolut wins. For sending $5,000 to family abroad, Wise often wins.
Revolut vs Traditional Banks: Traditional banks have branches, humans you can talk to, and decades of trust. They are slower, more expensive abroad, and their apps are boring. Revolut is faster, cheaper abroad, and way more fun to use. But it has no branches. If you need to deposit cash regularly, Revolut is painful.
Who Should Get Revolut, And Who Should Skip It?
Get Revolut if:
- You travel internationally, even 2 times a year
- You get paid in one currency and spend in another
- You are a freelancer or digital nomad
- You want instant notifications, virtual cards, and budgeting tools
- You want stocks and crypto in the same app as your bank
Skip Revolut if:
- You only bank in one country and never travel
- You need to deposit cash often
- You want to walk into a branch and talk to a human
- You are in the US and want a fully licensed US bank right now
So, is Revolut a good digital
banking app in 2026?
Yes. It is the best all-in-one money app for most people, especially if you travel, live across currencies, or hate traditional bank fees.
It is now a fully licensed bank in the UK and Europe, with FSCS protection up to £120,000, it is profitable, it has 68 million plus customers, and its free plan is genuinely useful, not a useless demo.
Just use it smartly. Use it for spending, travel, and daily money. Keep a backup bank for your salary and rent, just in case. And never exchange currency on a weekend on the free plan.
If you do that, Revolut will save you money, time, and a lot of airport stress.